 CompanyGraph
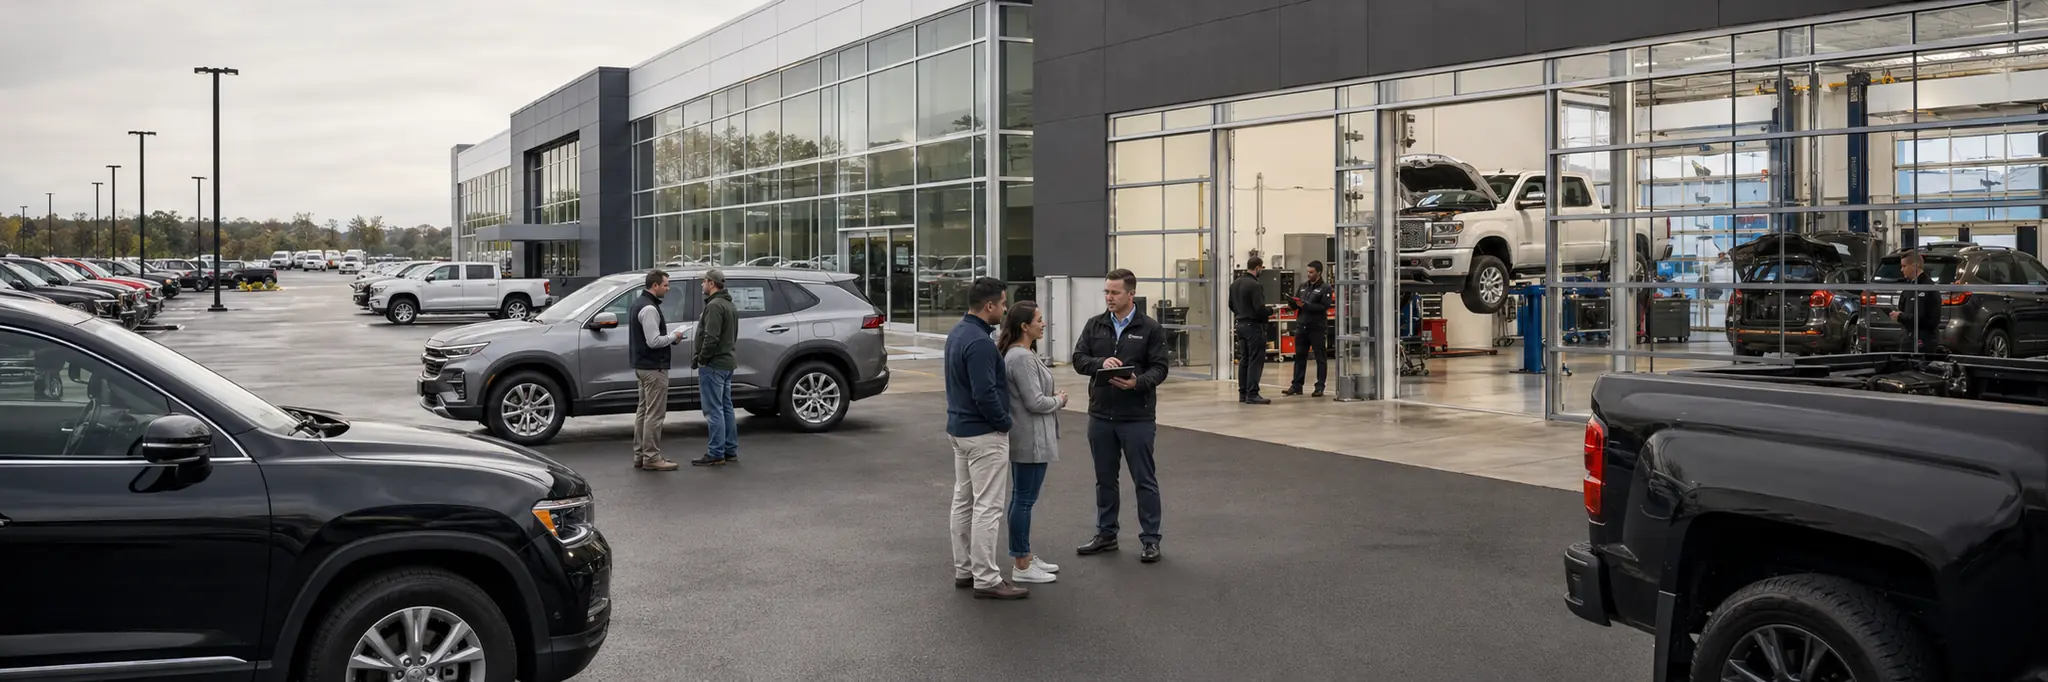
Franchise agreements and floor plan financing costs bind dealership economics to manufacturer allocation terms and inventory velocity, concentrating margin in aftermarket service rather than new vehicle sales.
Auto and truck dealerships operate the retail distribution layer between vehicle manufacturers and end buyers, bundling several coordination functions into a local point of contact: inventory holding, test-drive facilitation, financing arrangement, trade-in absorption, and ongoing mechanical service. The transformation converts wholesale manufacturer inventory into completed consumer transactions through a process that extends from initial presentation through financing, documentation, and delivery.
The industry's economic structure is layered. New vehicle sales, the most visible activity, generate structurally thin margins constrained by manufacturer pricing and competitive transparency. The primary profit sources are finance and insurance products attached to vehicle transactions, used vehicle operations where pricing is less transparent, and service departments generating recurring revenue at higher margins. This layered structure means that new vehicle sales function partly as a customer acquisition mechanism for more profitable downstream activities.
The franchise system defines the governance framework. Manufacturers grant territorial rights and impose facility, staffing, and performance standards, while dealers commit capital to inventory, real estate, and brand-specific infrastructure. Floor plan financing for vehicle inventory creates carrying cost pressure tied to interest rates and unit turn velocity. Scale provides advantages in financing terms, manufacturer allocation leverage, and back-office consolidation, while single-point operators depend more heavily on local market conditions and the service and used vehicle operations that generate the majority of their profitability.
Structural Role
Operates the retail distribution layer between vehicle manufacturers and end buyers, bundling inventory holding, financing arrangement, trade-in processing, and ongoing mechanical service into a local point of contact that solves the last-mile coordination problem of vehicle sales and ownership support.
Scale Differentiation
Large dealership groups operate across dozens or hundreds of locations spanning multiple brands and geographies, gaining leverage in floor plan financing, manufacturer allocation negotiations, and back-office consolidation. Mid-size groups cluster locations within a region, building brand density and local market share while maintaining multi-brand portfolios. Single-point operators depend heavily on their specific franchise relationship and local conditions, with service and used vehicle operations often constituting the largest share of profitability.
Financial Profile
Measured across the 44 companies in this industry with recorded financial statements. Each band spans the middle 90% of companies — 5th to 95th percentile — with the mark at the median. How wide a band runs is itself a reading: a tight band means the industry imposes its economics on every member; a wide one means outcomes differ sharply between its strongest and weakest companies.
Profitability
Gross margin16.5%median
8.4%62.7%
Operating margin4.1%median
0
-2.1%26.8%
Net margin2.3%median
0
-5.4%17.1%
Returns & efficiency
Return on equity9.3%median
0
-26.5%41.7%
Asset turnover1.33×median
0.22×2.53×
Free cash flow / revenue2.0%median
0
-31.8%19.6%
Balance sheet
Current ratio1.20×median
0.73×4.18×
Debt to equity1.07×median
0.04×4.10×
Reinvestment & payout
Capex / revenue1.2%median
0.2%15.4%
What marks this industry
Where this industry’s typical company sits against the typical company in every other industry we measure — metric by metric.
Asset turnover
1.33×typical industry 0.59×
7th highest of 101 industries with this measure.
Debt to equity
1.07×typical industry 0.37×
8th highest of 102 industries with this measure.
Net margin
2.3%typical industry 5.4%
9th lowest of 101 industries with this measure.
Gross margin
16.5%typical industry 29.4%
9th lowest of 101 industries with this measure.
Scale
39
companies with recorded market value
$1.2B
median company · global median $1.2B
$230M – $9.5B
middle 90% of companies
$186.7B
combined market value
The largest member carries roughly 44% of the combined market value; half the companies sit under $1.2B.
Valuation ranges
Price to book2.00×median
0.58×9.60×
Price to earnings16.34×median
7.16×83.30×
EV / EBITDA bands are not drawn for this industry. Many members run negative values there, and a percentile band across mixed signs has no honest reading — a range is shown only where it means something.
Bands are 5th–95th percentiles across this industry’s companies, computed from reported financial statements. Ratios are currency-free; money values are USD-normalized. These distributions describe how the industry is shaped — they are not a rating of it, and a company’s position inside them is not a forecast. Benchmark set computed 18 September 2026.
Connected Industries
Advertising Agencies
Creates demand for
Local and regional advertising
Auto Manufacturers
Creates demand for
Purchases vehicle inventory from OEMs
Auto Parts
Creates demand for
Service department parts purchasing
Credit Services
Creates demand for
Consumer vehicle financing
Insurance Property & Casualty
Creates demand for
Vehicle insurance at point of sale
Stocks
ACV Auctions Inc.
ACVA
Asbury Automotive Group Inc.
ABG
AutoNation Inc.
AN
Autostreets Development Ltd.
2443
Bilia AB
BILI.A
Bintang Oto Global Tbk.
BOGA
Camping World Holdings Inc.
CWH
CarGurus, Inc.
CARG
CarMax Inc.
KMX
Cartrade Tech Ltd.
CARTRADE
Carvana Co.
CVNA
Catarc Automotive Proving Ground Technology Co., Ltd.
301215
China Auto Logistics Inc.
CALI
Delek Automotive Systems Ltd.
DLEA
Dogus Otomotiv Servis ve Ticaret A.S.
DOAS
Driven Brands Holdings Inc.
DRVN
Fujian Zhangzhou Development Co., Ltd.
000753
Group 1 Automotive Inc.
GPI
Guan Chao Holdings Ltd.
1872
Idom Inc.
7599
Inchcape plc
INCH
Indomobil Sukses Internasional Tbk
IMAS
K Car Co., Ltd.
381970
Liaoning Shenhua Holdings Co., Ltd.
600653
Lithia Motors Inc.
LAD
Mitra Pinasthika Mustika Tbk
MPMX
Openlane Inc.
OPLN
Openlane Inc.
KAR
Oriental Holdings Berhad
4006
Pan German Universal Motors
2247
Penske Automotive Group Inc.
PAG
RideNow Group, Inc.
RDNW
Rush Enterprises Inc.
RUSHA
Rush Enterprises Inc.
RUSHB
Sinomach Automobile Co. Ltd.
600335
Sonic Automotive Inc.
SAH
Valvoline Inc.
VVV
Vertu Motors plc
VTU
Vicom Ltd.
WJP
VT Holdings Co., Ltd.
7593
Zhongsheng Group Holdings Limited
0881