 CompanyGraph
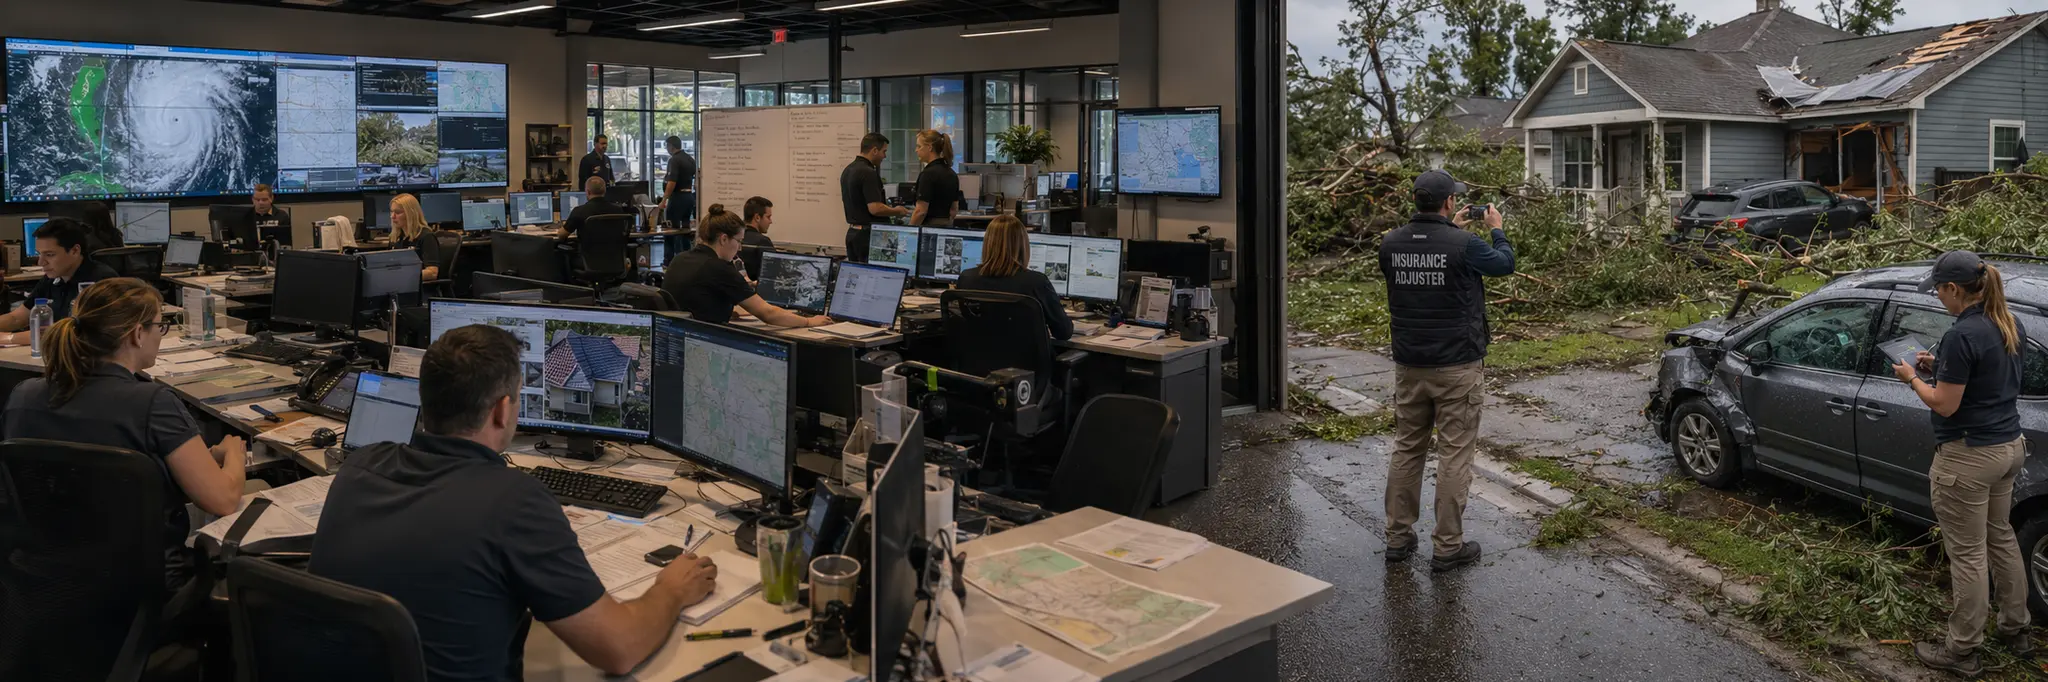
Catastrophic events create correlated losses across many policies simultaneously, while underwriting cycles alternate between hard and soft markets based on industry capital levels and recent loss experience.
Property and casualty insurance companies protect individuals and businesses against financial losses from property damage, legal liability, and casualty events. Product lines include homeowners, auto, commercial property, general liability, workers compensation, and professional liability coverage. The industry exists to transfer concentrated financial risk from policyholders to underwriters who can absorb it through diversification across large policyholder pools and multiple coverage lines.
Unlike life insurance with its multi-decade liability durations, P&C policies are typically annual, creating a shorter feedback loop between pricing decisions and loss experience. This shorter cycle drives underwriting cycles where periods of profitable underwriting attract capital and competition, depressing prices until losses accumulate and force correction. Catastrophe exposure is the defining tail risk, as hurricanes, earthquakes, wildfires, and other large-scale events create correlated losses across many policies simultaneously, potentially exceeding years of accumulated premium. Managing this concentration through geographic diversification, reinsurance, and catastrophe modeling is a core capability requirement.
Claims management is operationally intensive, requiring assessment of damage, determination of coverage applicability, and negotiation of settlement amounts across potentially millions of individual claims. Claims cost trends, particularly in liability lines where legal costs and jury awards are factors, introduce inflation dynamics specific to insurance that often exceed general price levels. Regulatory rate approval processes constrain the speed at which insurers can adjust pricing to reflect changing loss patterns, creating periods where underwriting margins compress before corrective pricing can take effect.
Structural Role
Absorbs and disperses property and liability risk by pooling premiums across policyholders, enabling individuals and businesses to transfer concentrated financial exposure from property damage, legal liability, and casualty events to a diversified underwriting entity capable of absorbing losses through portfolio-level risk management.
Scale Differentiation
Large P&C insurers spread catastrophe exposure across broader geographic and product portfolios and access reinsurance markets on favorable terms, using scale to absorb loss volatility across cycles. Mid-size carriers specialize in specific lines where deep underwriting expertise drives superior loss selection. Smaller companies compete in niche or regional markets where local relationships and specialized knowledge of specific risk classes provide pricing advantages that generalist competitors cannot match.
Connected Industries
Auto & Truck Dealerships
Creates demand for
Auto insurance demand tied to vehicle ownership
Capital Markets
Creates demand for
Invests premium float
Insurance Brokers
Creates demand for
Receives commercial policy placements from brokers
Insurance Reinsurance
Creates demand for
Cedes catastrophe and concentrated risk to reinsurers
Residential Construction
Creates demand for
New homes require property insurance
Stocks
American Coastal Insurance Corp.
ACIC
American Financial Group Inc.
AFG
American Integrity Insurance Group, Inc.
AII
Anicom Holdings Inc.
8715
Assurant Inc.
AIZ
Ategrity Specialty Holdings
ASIC
Bowhead Specialty Holdings Inc.
BOW
Chubb Limited
CB
Cincinnati Financial Corporation
CINF
CNA Financial Corporation
CNA
DB Insurance Co., Ltd.
005830
Definity Financial Corp.
DFY
Donegal Group Inc.
DGICA
First Insurance Co. Ltd.
2852
Gjensidige Forsikring ASA
GJF
Hagerty, Inc.
HGTY
Hanover Insurance Group, Inc.
THG
Hanwha General Insurance Co., Ltd.
000370
HCI Group Inc.
HCI
Heritage Insurance Holdings, Inc.
HRTG
Heungkuk Fire & Marine Insurance Co., Ltd.
000540
Hippo Holdings Inc.
HIPO
Hiscox Ltd
HSX
Horace Mann Educators Corp.
HMN
Hyundai Marine & Fire Insurance Co., Ltd.
001450
Intact Financial Corporation
IFC
Kemper Corporation
KMPR
Kingstone Companies Inc.
KINS
Kinsale Capital Group Inc.
KNSL
Lemonade Inc.
LMND
Línea Directa Aseguradora, S.A.
LDA
Loews Corporation
L
LPI Capital Berhad
8621
Mercury General Corporation
MCY
Old Republic International Corp.
ORI
Palomar Holdings Inc.
PLMR
People's Insurance Company (Group) of China Limited
1339
PICC Property and Casualty Company Limited
601319
ProAssurance Corporation
PRA
Progressive Corporation
PGR
REVO Insurance S.p.A.
REVO
RLI Corp.
RLI
Root, Inc. Class A Common Stock
ROOT
Safety Insurance Group Inc.
SAFT
Samsung Fire & Marine Insurance Co., Ltd.
000810
Selective Insurance Group Inc.
SIGI
Shinkong Insurance Co., Ltd.
2850
Skyward Specialty Insurance Group, Inc.
SKWD
Slide Insurance Holdings, Inc.
SLDE
Stewart Information Services Corporation
STC
Taiwan Fire & Marine Insurance Co., Ltd.
2832
The Allstate Corporation
ALL
The Travelers Companies, Inc.
TRV
Trupanion Inc.
TRUP
Turkiye Sigorta A.S.
TURSG
United Fire Group, Inc.
UFCS
Universal Insurance Holdings, Inc.
UVE
Wesure Global Tech Ltd.
WESR
W.R. Berkley Corporation
WRB
ZhongAn Online P&C Insurance Co., Ltd.
6060