 CompanyGraph
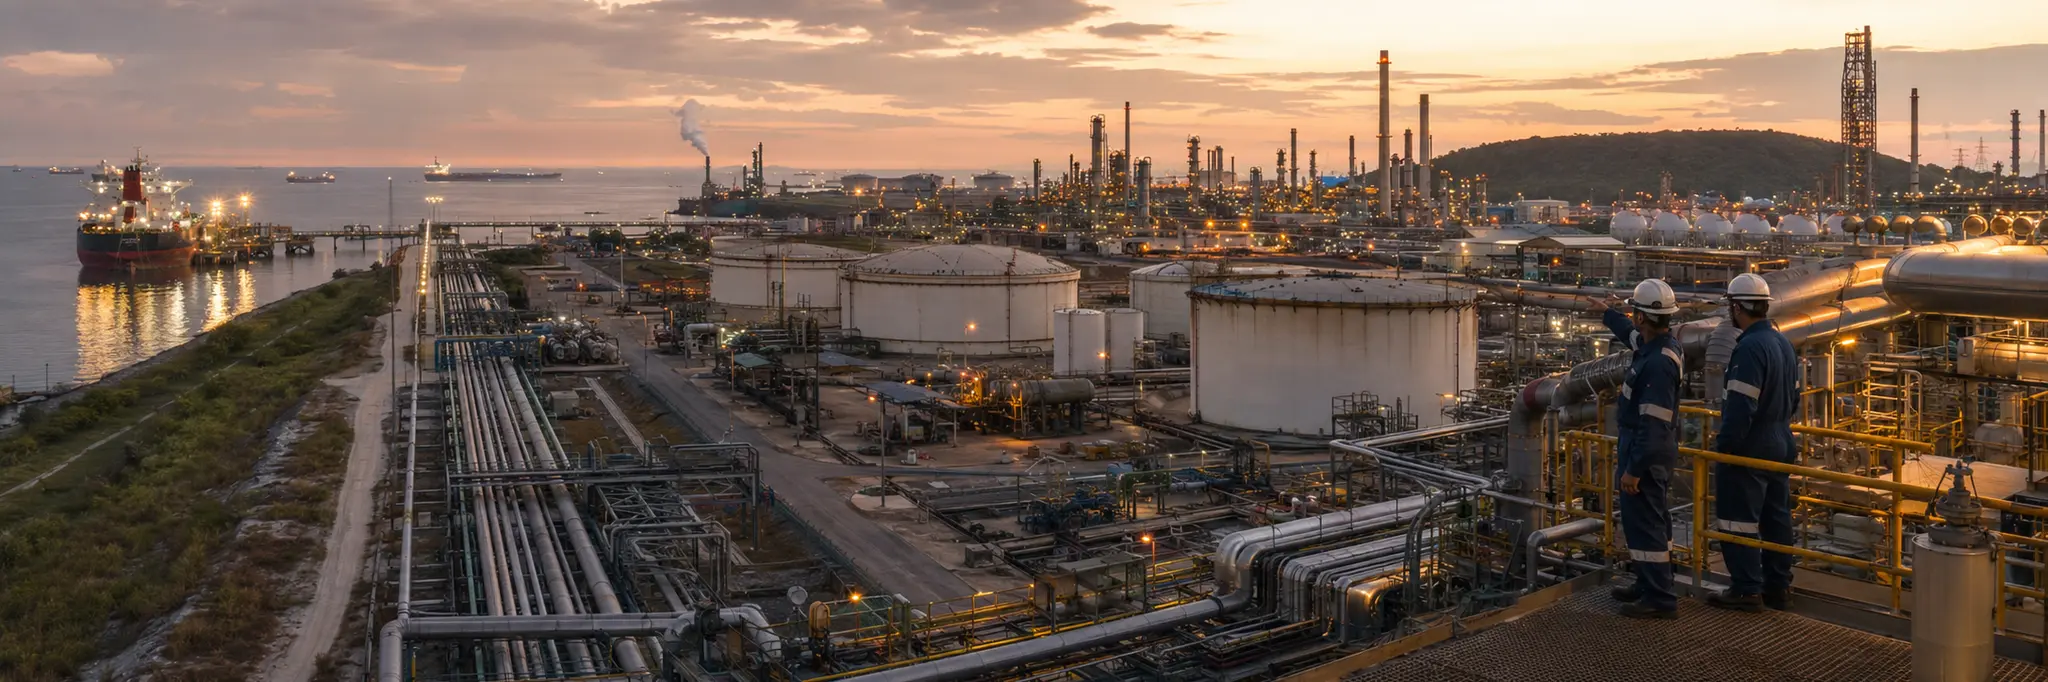
Vertical integration across the hydrocarbon value chain partially hedges commodity price volatility by capturing offsetting upstream and downstream margins, constrained by large, long-duration capital commitments across all segments.
Integrated oil and gas companies operate across the full hydrocarbon value chain: exploring for and producing crude oil and natural gas upstream, transporting and processing raw materials through midstream infrastructure, and refining crude into finished petroleum products for downstream distribution and sale. This vertical integration distinguishes them from pure-play exploration, midstream, or refining companies by combining multiple transformation stages within a single organizational structure.
The upstream segment is capital-intensive and directly exposed to commodity price risk, with geological uncertainty meaning substantial exploration investment may yield no commercial discovery. The downstream segment operates on different economics, where refining margins depend on the spread between crude input costs and refined product prices. This partial decoupling from crude prices provides some natural hedging within the integrated model, as upstream and downstream margins can move inversely with commodity price changes.
As a vertically integrated structure spanning extraction through retail, the integrated model requires organizational scale to coordinate across all value chain segments. Environmental regulation, emissions standards, and energy transition policy affect current operating costs and long-term capital allocation across every stage, while the large, long-duration, and partially irreversible nature of capital commitments across the value chain defines the industry's investment cycle and risk profile.
Structural Role
Coordinates the extraction, processing, and distribution of hydrocarbon energy across the full value chain from subsurface reservoir to end consumer, using vertical integration to manage commodity price exposure and capture margin across multiple transformation stages.
Scale Differentiation
Large integrated companies use downstream operations to partially offset upstream commodity volatility and deploy balance sheet capacity for capital-intensive mega-projects spanning exploration, production, refining, and distribution. Mid-size integrated firms focus on specific basins or regional value chains where operational depth compensates for narrower geographic coverage. The integrated model itself requires organizational scale, as coordinating exploration, production, refining, and distribution demands breadth that smaller firms cannot sustain.
Constraint Archetype
Depleting Extractive
A regime where the core productive asset is a finite, non-renewable resource that permanently diminishes with each unit extracted, making reserve replacement the dominant economic constraint.
Throughput-Bound Conversion
A regime where the rate at which physical inputs can be converted into outputs through fixed-capacity plant defines the economic ceiling.
Financial Profile
Measured across the 32 companies in this industry with recorded financial statements. Each band spans the middle 90% of companies — 5th to 95th percentile — with the mark at the median. How wide a band runs is itself a reading: a tight band means the industry imposes its economics on every member; a wide one means outcomes differ sharply between its strongest and weakest companies.
Profitability
Gross margin27.0%median
9.9%76.5%
Operating margin10.9%median
3.4%43.1%
Net margin7.5%median
1.0%26.1%
Returns & efficiency
Return on equity11.8%median
2.7%33.9%
Asset turnover0.68×median
0.26×1.32×
Free cash flow / revenue3.6%median
0
-11.6%25.5%
Balance sheet
Current ratio1.15×median
0.52×3.37×
Debt to equity0.48×median
0.06×1.10×
Reinvestment & payout
Capex / revenue7.1%median
0.2%28.2%
Dividend payout56.0%median
6.3%268.6%
What marks this industry
Where this industry’s typical company sits against the typical company in every other industry we measure — metric by metric.
Return on equity
11.8%typical industry 7.1%
10th highest of 102 industries with this measure.
Current ratio
1.15×typical industry 1.58×
13th lowest of 102 industries with this measure.
Capex / revenue
7.1%typical industry 3.8%
18th highest of 101 industries with this measure.
Scale
31
companies with recorded market value
$23.7B
median company · global median $1.2B
$729M – $345.9B
middle 90% of companies
$2.6T
combined market value
The largest member carries roughly 25% of the combined market value; half the companies sit under $23.7B.
Valuation ranges
Price to book1.48×median
0.24×3.79×
Price to earnings12.38×median
2.35×38.63×
EV / EBITDA5.90×median
0.77×15.19×
Bands are 5th–95th percentiles across this industry’s companies, computed from reported financial statements. Ratios are currency-free; money values are USD-normalized. These distributions describe how the industry is shaped — they are not a rating of it, and a company’s position inside them is not a forecast. Benchmark set computed 18 September 2026.
Connected Industries
Airlines
Supplies inputs to
Produces jet fuel consumed by airlines
Chemicals
Supplies inputs to
Refining produces petrochemical feedstocks
Oil & Gas Drilling
Creates demand for
Oil & Gas Equipment & Services
Creates demand for
Oil & Gas Midstream
Supplies inputs to
Production feeds midstream transportation networks
Trucking
Supplies inputs to
Produces diesel fuel for freight transportation
Utilities Regulated Gas
Supplies inputs to
Stocks
Bashneft Public Joint Stock Company
BANE
BP p.l.c.
BP
Caspian Sunrise plc
CASP
Cenovus Energy Inc.
CVE
Chevron Corporation
CVX
China Petroleum & Chemical Corporation
600028
Diversified Energy Company PLC
DEC
Edison S.p.A.
EDNR
Eni S.p.A.
ENI
Equinor ASA
STOHF
Exxon Mobil Corporation
XOM
Galp Energia, SGPS, S.A.
GALP
Gazprom PJSC
GAZP
Guanghui Energy Co., Ltd.
600256
Hellenic Energy Holdings S.A.
ELPE
Imperial Oil Limited
IMO
John Wood Group PLC
WG
Lukoil PJSC
LKOH
National Fuel Gas Company
NFG
National Gas & Industrialization Company
2080
Oil Country Tubular Ltd.
OIL
Oil & Natural Gas Corporation Ltd.
ONGC
OMV Petrom S.A.
XNE
PetroChina Company Limited
601857
PETROCN80
PETROCN80
Petroleo Brasileiro S.A.
PETR3
Quadrise PLC
QED
Repsol S.A.
REP
Shell plc
SHEL
Sichuan Shengda Forestry Industry Co. Ltd.
002259
Suncor Energy Inc.
SU
Surgutneftegas Public Joint Stock Company
SNGS
Tatneft PJSC
TATN
TotalEnergies SE
TTE
Transportadora de Gas del Sur S.A.
TGSU2
Yakutsk Fuel and Energy Company PJSC
YAKG
YPF S.A.
YPFD
Zhongman Petroleum and Natural Gas Group Corp., Ltd.
603619